Aging comes with many annoyances. Most come with signs and symptoms, or preventive checks from various markers could provide an early heads-up to cause some level of panic. But the most insidious types are those where NOTHING is noticed.
If one were to poke the eyeball, do we feel pain? In some movies, a person is being tortured with some scary looking object, threatening to pierce the eyeball. We feel so much pain even before it has breached. Cringe. But it seems there is no sensation to be felt on the eyeball itself?
In any case, it was a serendipitous circumstance that led wifey to pay a visit to an ophthalmologist. Turns out the amazing scanner the ophthalmologist had picked up an object floating above the retina. It looked like a UFO flying above a planet when a picture of it is taken from outer space.
Turns out she had experienced a retinal tear without detachment. No sensation whatsoever. When asked what the consequence could be, we were told, "Blindness". That sure was an absolute bummer.
The good news was, the doc could fix it. All it needed was to laser around the torn area to fuse it back. We were lucky it was detected early. All hail modern science!
And when asked when could we get it done, he said, "Immediately". Wah! One hour and with temporary blurred vision later, wifey emerged from the procedure at the hospital laser lab at the next building, all done.
Seems like it could be covered by the Integrated Shield Plus programme that wifey had too. Fully covered. And it was a breeze as the hospital admission could simply do an "E-filing". No additional information was required. Easy breezy. All hail Smart Nation and digitised government healthcare system!
Watch your fragile eyeballs!

Investment through the ages, from cradle to grave.
Showing posts with label Health. Show all posts
Showing posts with label Health. Show all posts
21 October 2019


30 September 2017
Losing Weight is an Expensive Affair - Or Not?
There's somehow this idea that to lose weight, one needs to eat "healthy food" and that costs more. That's a whole load of crap! Perpetrated by those who want to profit from the ill informed.
It's a matter of eating less (which is actually enough), coupled with exercise. Everything consumed should be in moderation. For the occasional binge, exercise more. A lot more. So if you're eating less, shouldn't it cost less?
There's is really no need for all the fads of specialty diets. No need for some miracle "weight loss" chemicals.
But I have heard of an interesting explanation from a friend though. He never could find the motivation to eat less, exercise more. Instead, he found it works when it hurts his pocket. So he signed onto a programme. Because he has to pay for it, he felt compelled to follow through. I guess that's one way.
I know of a relative who said she was dieting. She skipped rice and ate everything else in moderation. Yet, she was not losing any weight. I wondered why. Found out the reason. She didn't mentioned she binged on potato chips in between meals! Guess what? 20 chips is about 150 calories. That's 3,000 steps of walking to get rid of (roughly, 20 steps = 1 calories). It all adds up. Munch on a packet worth and that's probably the whole day's intact allowance! No wonder her so-called 'diet' wasn't working.
Check out "Basal Metabolic Rate" on the Internet. It's a good topic to start with. Simple maths. Or chemistry. Or biology. Depending on how you prefer to read it.
Was having a Classic Angus burger at Hungry Jacks in the Land of Oz (Burger King in Singapore), it's apparently close to 1,000 calories. And that's without even the fries and soda! Phew. That's half a day worth of intake for most people. The koalas have it good. They munch and sleep all day, get fat, and still look cute.

But I'm no koala. Time to go for a walk ...
18 November 2016
Health365 and Counting
So I've been trying to clock 5,000 to 10,000 steps per day to walk off the calories. The logic being that 5,000 steps is approximately 250 calories expended. Doing that 30 days a month equates to 7,500 calories, which is about 1 kg of weight. [More on this: Investing and dieting - wealth and health]
It's not too difficult to reach 5,000 steps a day really. Walk to the MRT on the way to work. Walk out for lunch and back (I know, weather might suck). And again from MRT to home at the end of the day. A little each way and it all adds up.
But reaching 10,000 is an altogether different challenge. It means deliberately walking from the office to the MRT station without taking the feeder bus. In terms of time, it takes only marginally a few minutes longer. So it's not really a hustle. But it is a hustle doing so in working attire with a load in my bag, especially the laptop. Back-breaking killer.
I guess it helps to fiddle with the phone, catching a few pokemons and swiping at pokestops along the way. A mild distraction.
Wouldn't it be great if one could make some money doing this as well? Actually, there is. Not much, just a little.
The Health Promotion Board (HPB) started another season of the National Step Challenge not too long ago. All I needed to do was to download the Health365 app from the AppStore, and sign up for the challenge. With the S-Health app on my phone that does the step counting, I only needed to run the Health365 on some days to sync the step count.
[There's an alternative option of getting a free step counting device (Fitbit-like or a watch type) from HPB.]
The steps are accumulated. So every step counts. There are several levels of rewards as certain step counts are reached. A few click on the Health365 app on the Rewards page and an NTUC voucher gets mailed to me a few weeks later.
Free money for doing nothing more than keeping up my health. Isn't it great? Stay healthy yah.
21 September 2016
How Much Cash is Needed for a Hospitalisation?
So my aged mother had a fall. She is statistically above average in age. It's a blessing that she has been largely well all these years. But it had to happen, sooner or later. Any fall at this advanced age is likely to have consequences.
She has decided to forego an operation given her age. And she'd rather live with the pain and a slow recovery (if ever), rather than subject herself to the risk of an operation.
It's been a fortnight of hospital stay, followed by weeks in the rehabilitation ward at the adjoining community hospital. Hospitals can be quite seamless with this modern clustering design.
Class C ward can be a very noisy affair at the primary care hospital. Lots of fellow patients groaning throughout the day and night, the occasional smell of overflowed urine, the psychological fear when there is an unfortunate death, etc. Many negatives.
But the rehab ward was a different matter altogether - significantly quieter, a lot more airy, spacious and fascinating layout of eating and resting spaces that try to prepare the patient towards conditions that are closer to the home feel. The nursing care has been quite an eye opener and pleasant surprise. Such cheery looking staff! They are wonderful people.
What's the financial damage? Well, for a Class C ward, the total bill after Medishield was a few thousand dollars which was taken care of by Medisave. So that's been zero cash outlay so far. It's so important that we have these safety buffers.
15 June 2015
24 Tales in the Journey to Wealth
RETIREMENT
"Financial Independence, Retire Early" (FIRE) - that seems like a wonderful catch phrase to set the flames going. What does it take to achieve this burning desire? I think it boils down to a magic number.
[1. http://lizardorealm.blogspot.sg/2015/05/light-fire-can-i-retire-now.html]

STOCKS
Singapore Savings Bond.
This offering from the Singapore Government will be available to retail investor soon. While not a inflation-linked bond, it has some semblance of it. I will most certainly park some of my cash components here. That will serve as an emergency buffer that can be cashed out if needed.
[7. http://lizardorealm.blogspot.sg/2015/04/singapore-savings-bond-as-safe-as-it.html]
Central Provident Fund (CPF).
The compulsory savings into CPF actually is another bond component, offering steady and fairly risk-free growth. The only problem is the lock-in. The lock-in becomes less of a worry for someone like me who is reaching the half-century mark. CPF funds has serveed many useful purposes thus far, especially to fund housing (used), support the kids' education (an option not yet used), or invested into stock or unit trust funds if I prefer to take more risks.
[8. http://lizardorealm.blogspot.sg/2015/02/a-great-retirement-offer-from-cpf.html]
Even as the investment portfolios are being built up, it is also worthwhile to examine options to reduce 'leakages'.
Supplementary Retirement Scheme (SRS).
Taxation is such a killer, especially at higher incomes. One sure way to reduce the tax burden is to contribute to the SRS (and invest the money sitting in SRS!).
[10. http://lizardorealm.blogspot.sg/2015/02/one-way-to-avoid-paying-more-tax-srs.html]
Donations.
And if you have a charitable heart, donation is another way of reducing the tax burden while doing some good deeds.
[11. http://lizardorealm.blogspot.sg/2015/02/another-way-to-avoid-paying-more-tax.html]
Credit Cards.
Some people view credit cards as an evil thing. But used wisely, it can actually help reduce our expenses.
[12. http://lizardorealm.blogspot.sg/2015/06/4-credit-cards-with-great-cashbacks-and.html]
EXOTICS & ALTERNATIVES
There are many exotic options and alternatives to grow that investment pie. But be very careful! Perhaps, it suffices to keep things simple.
Crowdfunding.
A recent trend has been the growth of crowd-funding platforms. These have arrived on our shores, offering the lure of 12% returns or more. In reality, they are even more risky than junk bonds. I am keeping this in view for now.
[13. http://lizardorealm.blogspot.sg/2015/02/moolahsense-embarks-on-new-fundraising.html]
Starting a Business.
This requires more careful considerations. I'm not quite ready for that leap.
[14. http://lizardorealm.blogspot.sg/2015/01/running-cafes-as-business-owner.html]
Exciting Bank Offers.
This is an oxymoron. With the exception of the aforementioned special savings accounts, what can they offer that can do better than all the self-help options mentioned earlier given their exorbitant charges?
[16. http://lizardorealm.blogspot.sg/2015/05/a-fantastic-investment-deal-at-bank-or.html]
STAY HEALTHY
Be Healthy.
Most importantly, is to stay healthy. What's the point of an early retirement, if one is in bade health? Or worse, expired early!
[17. http://lizardorealm.blogspot.sg/2014/07/investing-and-dieting-wealth-and-health.html]
Medical Insurance.
But we can never be certain of good health. So medical insurance is a must in my view. Without this, all the savings and investments can be easily wiped out in no time. Sometimes, we really have to spend money to save money.
[18. http://lizardorealm.blogspot.sg/2015/04/thank-goodness-we-had-medical-insurance.html]
Staying Healthy on Cruise.
One can still enjoy life, even while on a food binge on a cruise. It's not that difficulty to stay healthy, really.
[19. http://lizardorealm.blogspot.sg/2015/04/not-too-difficult-to-stay-healthy-on.html]
ANTHOLOGY OF DISASTERS
Con Jobs.
These are just plentiful and are happening everyday. Always worth repeating the mantra, "if it sounds too good to be true, it probably is too good to be true". Greed is our greatest enemy. And the enemy is that person in the mirror.
[20. http://lizardorealm.blogspot.sg/2015/05/rags-to-riches-riches-to-rags.html]
[21. http://lizardorealm.blogspot.sg/2015/02/the-allure-of-gold-treachery-of-glitter.html]
Job Loss.
This can really be painful and disastrous. A family unit that has multiple wage earner helps diversify the risk. But for the single-income family, there really isn't any room. Best to move on and deal with the realities.
[22. http://lizardorealm.blogspot.sg/2015/05/what-do-you-do-if-you-get-laid-off.html]
Extravagance.
A lifestyle of living beyond one's means is a sure road to disaster. Live within your means. What you can't save isn't yours.
[23. http://lizardorealm.blogspot.sg/2015/05/a-millionaire-and-yet-completely-broke.html]
Careless Decisions.
Sometimes, we will make bad decisions and lose money. Hopefully, this doesn't happen too often and too painfully.
[24. http://lizardorealm.blogspot.sg/2015/06/sumiko-tans-money-no-enough.html]
--
"Good health, great wealth!"
Or should it be, "Good wealth, great health!"
"Financial Independence, Retire Early" (FIRE) - that seems like a wonderful catch phrase to set the flames going. What does it take to achieve this burning desire? I think it boils down to a magic number.
[1. http://lizardorealm.blogspot.sg/2015/05/light-fire-can-i-retire-now.html]

STOCKS
To achieve this outcome, I invest in the market, diversified across market regions, namely Asia Pacific (except Japan), global emerging markets, the US, Europe and Japan.
Unit Trust.
I use funds from the Supplementary Retirement Scheme (SRS) and CPF OA and SA funds to invest into Unit Trust on the Fundsupermart platform. Since each year I can contribute up to to $12,750 into SRS, that is the capital injection that goes into this portfolio. This unit trust portfolio is further complemented by ETFs. Fees in Unit Trusts are relatively higher compared to ETFs, but the latter tends to be less liquid.
Singapore Stocks.
A value investment approach in dividend paying stocks can be most rewarding. I diversify across the Singapore stock market by buying a dozen stocks (or two!) to spread the risks. The wonderful part of this is that I can happily collect dividends to reinvest while waiting as well. Of late, the dividends can run into an average of $1,000 a month. This will be the means by which I intend to generate the eventual passive income for retirement. The dividends would have been more, except that I typically take up the script offer (i.e. collect more units of stocks in lieu of cash), so as to continue to build up my portfolio, and at a discount from the market value.
[2. http://lizardorealm.blogspot.sg/2015/04/my-singapore-team-of-dividend-stocks.html]
US Stocks.
Likewise, for US stocks. I invest through POEMS which hold the US stocks as a custodian account. US stocks (if you pick carefully!) have a practice of steady dividend growth. So even if you do nothing, the dividends tend to hold stead or growth with each passing year. The only problem is the 30% withholding tax on the dividends. The custodian fee that POEMS charge is quite minimal really, so that I can live with.
[3. http://lizardorealm.blogspot.sg/2015/06/my-us-team-of-dividend-stocks-2015.]
Exchange Traded Funds (ETF).
Since I already hold diversified portfolios of Singapore and US stocks, the rest of the market regions are held via ETF, which complements the Unit Trust portfolio mentioned earlier. I prefer to hold ETFs that pay out dividends - or what I refer to as an Income ETF Portfolio.
BONDS
The stock portfolios are complemented by bonds and cash. While my plan was to maintain only 10% in bonds and cash (or bond-like instruments), it has typically reached 20%. In addition, I maintain 6 to 9 months worth of expenses in cash instruments.
Preference Shares and Retail Bonds.
These can be bought off the SGX. The coupon payments, usually half-yearly, provides yet another income stream.
[5. http://lizardorealm.blogspot.sg/2015/01/non-convertible-preference-shares.]
Bondsupermart.
More recently, a wider spread of bonds can also be bought through Fundsupermart. Aside from the few retail bonds, the majority will require hefty $250,000+ investments. Something beyond my reach and need for now, so it's something to keep in view as a future option. As an income stream, perpetual bonds can be quite attractive.
[6. http://lizardorealm.blogspot.sg/2015/05/bondsupermart.html]Bondsupermart.
More recently, a wider spread of bonds can also be bought through Fundsupermart. Aside from the few retail bonds, the majority will require hefty $250,000+ investments. Something beyond my reach and need for now, so it's something to keep in view as a future option. As an income stream, perpetual bonds can be quite attractive.
Singapore Savings Bond.
This offering from the Singapore Government will be available to retail investor soon. While not a inflation-linked bond, it has some semblance of it. I will most certainly park some of my cash components here. That will serve as an emergency buffer that can be cashed out if needed.
[7. http://lizardorealm.blogspot.sg/2015/04/singapore-savings-bond-as-safe-as-it.html]
Central Provident Fund (CPF).
The compulsory savings into CPF actually is another bond component, offering steady and fairly risk-free growth. The only problem is the lock-in. The lock-in becomes less of a worry for someone like me who is reaching the half-century mark. CPF funds has serveed many useful purposes thus far, especially to fund housing (used), support the kids' education (an option not yet used), or invested into stock or unit trust funds if I prefer to take more risks.
[8. http://lizardorealm.blogspot.sg/2015/02/a-great-retirement-offer-from-cpf.html]
Bank Savings Accounts.
Even the traditional banks can offer interesting saving accounts with higher interest rates. But a bit of acrobatics need to be done. This is the other component of my cash funds.
[9. http://lizardorealm.blogspot.sg/2015/06/how-can-we-stretch-interest-on-our-bank.html]
Even the traditional banks can offer interesting saving accounts with higher interest rates. But a bit of acrobatics need to be done. This is the other component of my cash funds.
[9. http://lizardorealm.blogspot.sg/2015/06/how-can-we-stretch-interest-on-our-bank.html]
MAXIMISING SAVINGS, REDUCING EXPENSES
Even as the investment portfolios are being built up, it is also worthwhile to examine options to reduce 'leakages'.
Taxation is such a killer, especially at higher incomes. One sure way to reduce the tax burden is to contribute to the SRS (and invest the money sitting in SRS!).
[10. http://lizardorealm.blogspot.sg/2015/02/one-way-to-avoid-paying-more-tax-srs.html]
Donations.
And if you have a charitable heart, donation is another way of reducing the tax burden while doing some good deeds.
[11. http://lizardorealm.blogspot.sg/2015/02/another-way-to-avoid-paying-more-tax.html]
Some people view credit cards as an evil thing. But used wisely, it can actually help reduce our expenses.
[12. http://lizardorealm.blogspot.sg/2015/06/4-credit-cards-with-great-cashbacks-and.html]
EXOTICS & ALTERNATIVES
There are many exotic options and alternatives to grow that investment pie. But be very careful! Perhaps, it suffices to keep things simple.
Crowdfunding.
A recent trend has been the growth of crowd-funding platforms. These have arrived on our shores, offering the lure of 12% returns or more. In reality, they are even more risky than junk bonds. I am keeping this in view for now.
[13. http://lizardorealm.blogspot.sg/2015/02/moolahsense-embarks-on-new-fundraising.html]
Starting a Business.
This requires more careful considerations. I'm not quite ready for that leap.
[14. http://lizardorealm.blogspot.sg/2015/01/running-cafes-as-business-owner.html]
Inheritance.
One could wait for an inheritance, if there is any to be had! But I wouldn't bet on this.
[15. http://lizardorealm.blogspot.sg/2014/12/20-years-and-200000-mothers-savings.html]
One could wait for an inheritance, if there is any to be had! But I wouldn't bet on this.
[15. http://lizardorealm.blogspot.sg/2014/12/20-years-and-200000-mothers-savings.html]
This is an oxymoron. With the exception of the aforementioned special savings accounts, what can they offer that can do better than all the self-help options mentioned earlier given their exorbitant charges?
[16. http://lizardorealm.blogspot.sg/2015/05/a-fantastic-investment-deal-at-bank-or.html]
STAY HEALTHY
Be Healthy.
Most importantly, is to stay healthy. What's the point of an early retirement, if one is in bade health? Or worse, expired early!
[17. http://lizardorealm.blogspot.sg/2014/07/investing-and-dieting-wealth-and-health.html]
Medical Insurance.
But we can never be certain of good health. So medical insurance is a must in my view. Without this, all the savings and investments can be easily wiped out in no time. Sometimes, we really have to spend money to save money.
[18. http://lizardorealm.blogspot.sg/2015/04/thank-goodness-we-had-medical-insurance.html]
Staying Healthy on Cruise.
One can still enjoy life, even while on a food binge on a cruise. It's not that difficulty to stay healthy, really.
[19. http://lizardorealm.blogspot.sg/2015/04/not-too-difficult-to-stay-healthy-on.html]
ANTHOLOGY OF DISASTERS
Con Jobs.
These are just plentiful and are happening everyday. Always worth repeating the mantra, "if it sounds too good to be true, it probably is too good to be true". Greed is our greatest enemy. And the enemy is that person in the mirror.
[20. http://lizardorealm.blogspot.sg/2015/05/rags-to-riches-riches-to-rags.html]
[21. http://lizardorealm.blogspot.sg/2015/02/the-allure-of-gold-treachery-of-glitter.html]
Job Loss.
This can really be painful and disastrous. A family unit that has multiple wage earner helps diversify the risk. But for the single-income family, there really isn't any room. Best to move on and deal with the realities.
[22. http://lizardorealm.blogspot.sg/2015/05/what-do-you-do-if-you-get-laid-off.html]
Extravagance.
A lifestyle of living beyond one's means is a sure road to disaster. Live within your means. What you can't save isn't yours.
[23. http://lizardorealm.blogspot.sg/2015/05/a-millionaire-and-yet-completely-broke.html]
Careless Decisions.
Sometimes, we will make bad decisions and lose money. Hopefully, this doesn't happen too often and too painfully.
[24. http://lizardorealm.blogspot.sg/2015/06/sumiko-tans-money-no-enough.html]
--
"Good health, great wealth!"
Or should it be, "Good wealth, great health!"
20 April 2015
Is it that Difficult to Stay Healthy While on a Cruise?
LadyIronChef blogged about 5 easy ways to exercise while on holidays. Essentially, the calories expended in the 5 activities look like this:
Walk - 3 hrs, 405 kcal
Hike - 2 to 3 hrs, 674 to 1014 kcal
Swim - 20 min, 115 kcal
Circuit around hotel room - 7 min, 58 kcal
Dance - 2 to 3 hrs, 930 to 1395 kcal
The above made me recall about my last cruise experience on board Royal Carribean's Mariner of the Seas.
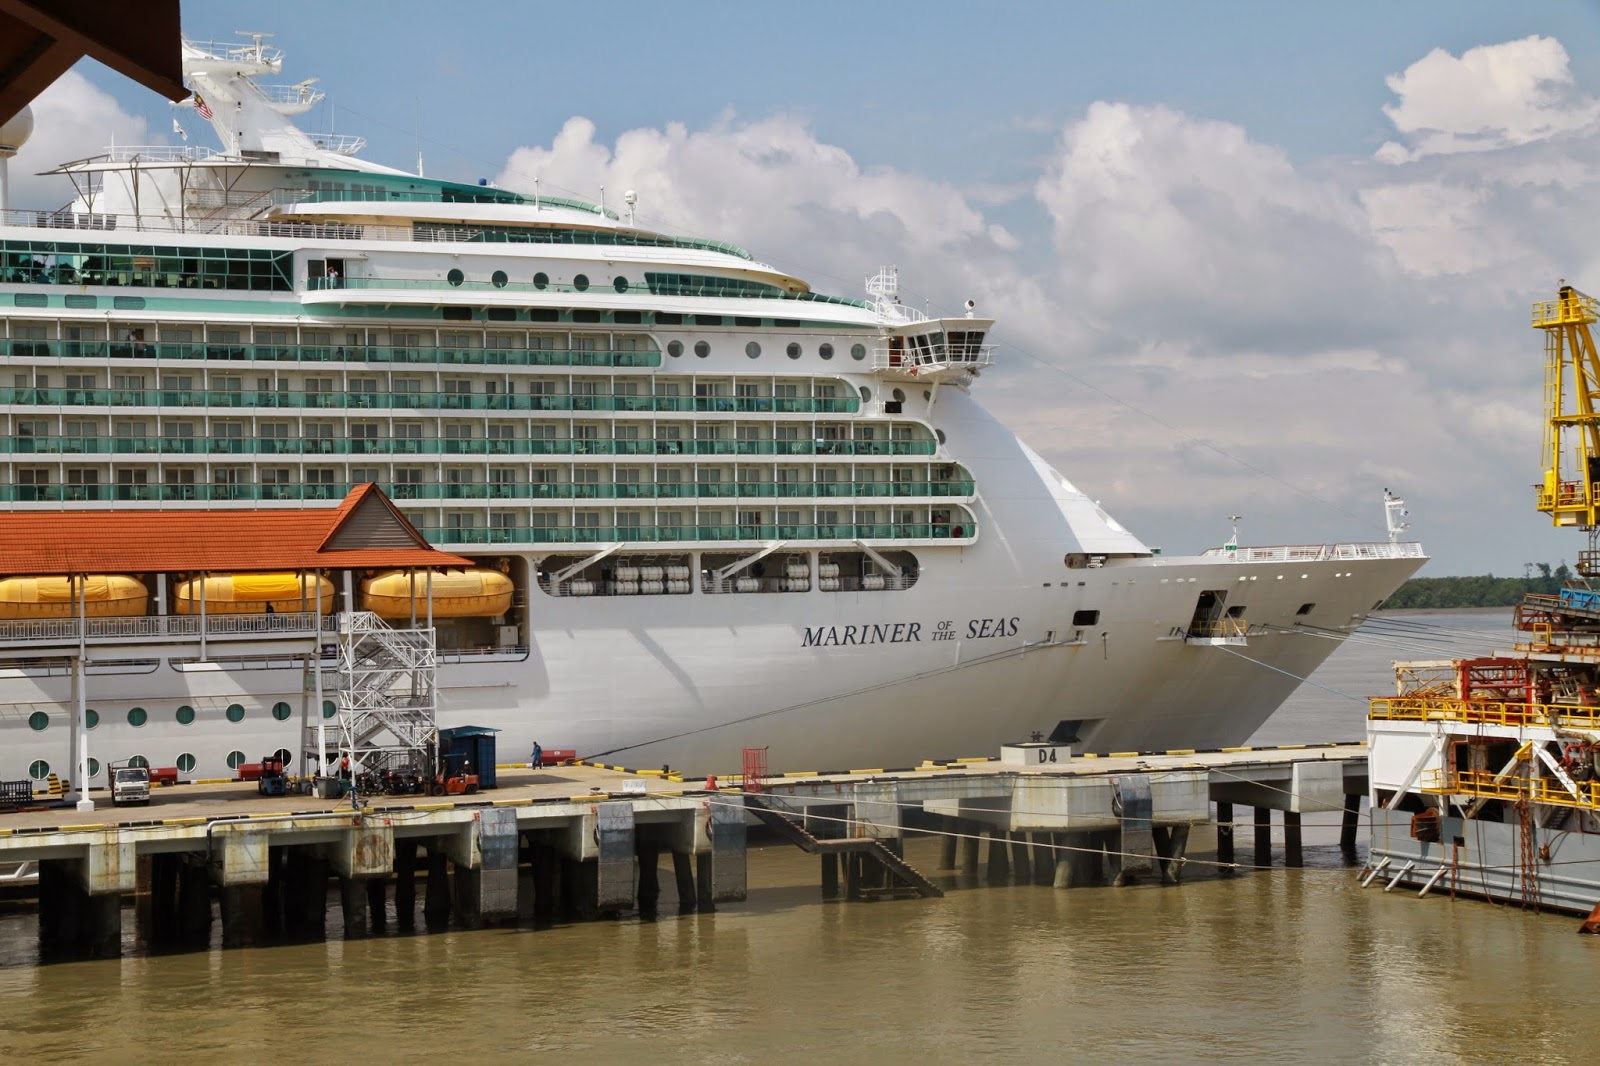
Great views and great entertainment, even if they're somewhat cabaret like. Shrek is the theme on board this ship.

As always for cruise, it was a food binge of immense proportions. Staying in a Grand Suite came with greater benefits, including the use of the VIP Lounge. That meant even more food! What's a cruise without the food?
I figured my daily food intake was in the region of 3,000 kcal. Maybe more. I could be in denial. Since my Basal Metabolic Rate was in the region of 2,000 kcal, that meant I had to exercise away 1,000 kcal per day. No small feat to achieve given that I only averaged 200 kcal on a normal working day, and perhaps closer to 500 kcal a day on weekends.
Turns out, it wasn't too difficult to accomplish on board the cruise ship. An hour per day in the gym clocked about 500 kcal. Walking to restaurants for meals and to various entertainments from the bow to the stern, and from the stern to the bow of the ship several times each day meant that I also clocked more than 10,000 steps per day. That works out to another 500 kcal or so. It's a lot of serious walking. There, 1,000 kcal a day expended to shed the excess.
No net weight gain. Pays to stay healthy. Exercise away for the good life.
Great health, good wealth! Enjoy your next cruise.
Walk - 3 hrs, 405 kcal
Hike - 2 to 3 hrs, 674 to 1014 kcal
Swim - 20 min, 115 kcal
Circuit around hotel room - 7 min, 58 kcal
Dance - 2 to 3 hrs, 930 to 1395 kcal
The above made me recall about my last cruise experience on board Royal Carribean's Mariner of the Seas.
Great views and great entertainment, even if they're somewhat cabaret like. Shrek is the theme on board this ship.
As always for cruise, it was a food binge of immense proportions. Staying in a Grand Suite came with greater benefits, including the use of the VIP Lounge. That meant even more food! What's a cruise without the food?
Turns out, it wasn't too difficult to accomplish on board the cruise ship. An hour per day in the gym clocked about 500 kcal. Walking to restaurants for meals and to various entertainments from the bow to the stern, and from the stern to the bow of the ship several times each day meant that I also clocked more than 10,000 steps per day. That works out to another 500 kcal or so. It's a lot of serious walking. There, 1,000 kcal a day expended to shed the excess.
No net weight gain. Pays to stay healthy. Exercise away for the good life.
Great health, good wealth! Enjoy your next cruise.
25 July 2014
Investing and Dieting - Same Rules, Different Games
My wife and I had the opportunity to do something on our own today and had a sumptuous lunch with a great view. We pretty much consumed our whole day's calorie intake from that one lunch. Guess it's time to hit the gym and swimming pool to make up for the overdose!
It got me into a train of thought about investing and dieting yet again.

My daily budget for food intake is akin to a monthly salary. They both set the opening budget to work within. Everything thereafter is about living within the budget, and/or increasing the budget to work with.
Consider this: My Basal Metabolic Rate is 1,950 kCal. Given the longer term aim to lose 2 kg a month (~7,000 kCal), the daily aim is then to lose 500 kCal a day. So I have two choices: eat less, or exercise more. I could either eat no more than 1,450 kCal a day, or exercise 500 kCal and eat up to 1,950 kCal. The answer, as always, is something in between. So, I've taken to exercising 300 kCal and eating up to 1,650 kCal each day.
This has a close parallel to investing. My monthly salary is $X. Given the longer term aim to achieve $1.8m portfolio to generate my retirement income upon retirement, the shorter term monthly aim is then to either put aside enough savings from my salary for investment (spend less), or to find other avenues to generate more income to work with (earn more). The first case of spending less would mean controlling what I spend on - some frugal discipline is needed given all the competing demands. For the second case of earning more, that could be from salary raise and bonus, dividend income, or any other sources of income.
I need to keep my intake within the daily calorie count in order not to gain weight. In fact, as I want to lose weight at a certain rate, it means I need to experience a net deficit.
If I might distill the above thought process therefore, it boils down to:
1. Establish the end goal - long term aim.
2. Break that down into more manageable shorter term budget.
3. Live within the budget.
4. Grow alternatives to expand the budget.
5. Stick to the plan.
Slow and steady as it goes, but surely and certainly the end goal will be met. Same rules, just different games.
Good health and great wealth.
Related:
Investing and Dieting - Wealth and Health
It got me into a train of thought about investing and dieting yet again.
My daily budget for food intake is akin to a monthly salary. They both set the opening budget to work within. Everything thereafter is about living within the budget, and/or increasing the budget to work with.
Consider this: My Basal Metabolic Rate is 1,950 kCal. Given the longer term aim to lose 2 kg a month (~7,000 kCal), the daily aim is then to lose 500 kCal a day. So I have two choices: eat less, or exercise more. I could either eat no more than 1,450 kCal a day, or exercise 500 kCal and eat up to 1,950 kCal. The answer, as always, is something in between. So, I've taken to exercising 300 kCal and eating up to 1,650 kCal each day.
This has a close parallel to investing. My monthly salary is $X. Given the longer term aim to achieve $1.8m portfolio to generate my retirement income upon retirement, the shorter term monthly aim is then to either put aside enough savings from my salary for investment (spend less), or to find other avenues to generate more income to work with (earn more). The first case of spending less would mean controlling what I spend on - some frugal discipline is needed given all the competing demands. For the second case of earning more, that could be from salary raise and bonus, dividend income, or any other sources of income.
I need to keep my intake within the daily calorie count in order not to gain weight. In fact, as I want to lose weight at a certain rate, it means I need to experience a net deficit.
If I might distill the above thought process therefore, it boils down to:
1. Establish the end goal - long term aim.
2. Break that down into more manageable shorter term budget.
3. Live within the budget.
4. Grow alternatives to expand the budget.
5. Stick to the plan.
Slow and steady as it goes, but surely and certainly the end goal will be met. Same rules, just different games.
Good health and great wealth.
Related:
Investing and Dieting - Wealth and Health
03 July 2014
Investing and Dieting - Wealth and Health
 The whole point of planning for a retirement income is to eventually achieve financial independence to retire on right? That means there is an inherent assumption that one gets to actually retire and live life to enjoy for "as long as you shall live", as my insurance agent might say. So one has to figure out what it takes to be healthy to do so.
Eat Less, Exercise More
Managing one's weight then goes a long way to achieving this goal. "Eat less, exercise more", or so goes conventional wisdom. But where's the joy if I love to eat in the first place? Easier said than done it seems.
Actually, my experience over the past half a year suggests that it really isn't that tough. There are really two important rules to remember to get started:
Rule #1. Basal Metabolic Rate (BMR). This is the daily calorie (kCal) intake that one needs to maintain the weight. There are several formulas. But no worries, just pick one and go with it. They are about the same anyway - a function of height, weight, age and sex. Simply said, if I eat more than the BMR level, I would gain weight. Conversely, eat less, and I lose weight. Simple.
Rule #2. 7000 calories = 2 pounds (or just under 1 kg). Therefore, if I maintain a net deficit vide Rule #1 over a period of time, I would lose almost 1 kg per 7000 calories of deficit. At a steady rate of 350 calories deficit a day, I would lose about 1 kg each fortnight.
Spend Less, Invest More
If you think about this, the whole concept isn't really that much different from investment - i.e. live within one's means. Overspend, and I end up in debt. Spend less, and there is savings. The Basal Metabolic Rate is similar to the idea of balancing our revenue and expenses.
And if I were to put aside a certain sum regularly, I would build up a healthy level of savings. Attempting to lose 350 calories a day to create about 2 kg weight loss a month is equivalent to putting aside a regular sum of savings into investments to build up a healthy portfolio.
Health is Wealth
It all goes together. I've shed 10 kg over the past 5 months. Join me?
Go go go!
Subscribe to:
Posts (Atom)